

BILL AP & AR Business Payments
by Bill.com Inc.
4.3
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.3
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I came away from BILL AP & AR with a fairly clear impression: it is most useful when bill payment and incoming payments are part of a regular business routine, not when you simply need another way to pay an occasional invoice. The app is built around business payments, and that focus makes it more practical than a general banking app for some workflows while also making it less appealing for people who want a broad personal-finance tool.
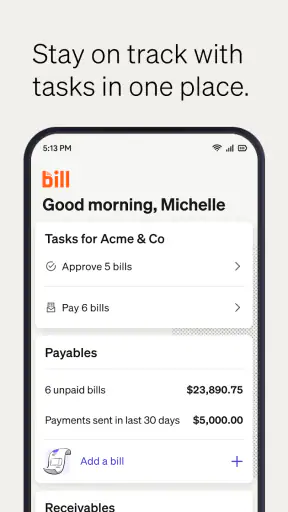
In everyday terms, this is a business app from Bill.com Inc. that brings accounts payable and accounts receivable tasks into a mobile setting. Its short store label, “BILL AP & AR,” is brief, but the important idea is the combination of paying bills and getting paid online. I found that combination more meaningful than either side on its own: a company can use one place to keep payment work moving instead of treating outgoing and incoming money as completely separate chores.
The app is free to install and has an Everyone content rating, which makes it easy to consider for a small business team. Its public reception is also encouraging, with a 4.3 average from around 7.5 thousand ratings and more than 500 thousand installs. Those figures do not make it automatically right for every company, but they do suggest that it has found a real audience among people handling business payments on mobile.
How BILL AP & AR fits into real business payment work
I find it useful to judge a business payment app by how well it fits the handoffs around a payment, not just by whether it can move money. In the next section, I’ll look at the moments when bringing bills and receivables into a mobile routine can help, and the practical checks I’d keep in place so convenience doesn’t replace sound review.
A practical mobile companion for accounts payable
The strongest case for this app is the business owner or finance worker who does not want payment duties tied to a desk. If an invoice needs attention while you are away from the office, a mobile-first payment tool can reduce the delay between noticing the bill and dealing with it. That matters more than it sounds. A payment workflow that waits until the end of the day can easily become a workflow that waits until the end of the week.
I would think of BILL AP & AR as a control point for payment tasks rather than as a replacement for every financial system a company may use. Its value comes from giving business payments a dedicated home, with the accounts payable side aimed at money going out and the accounts receivable side aimed at money coming in. That separation is useful because the two jobs require different kinds of attention, even when the same person handles both.
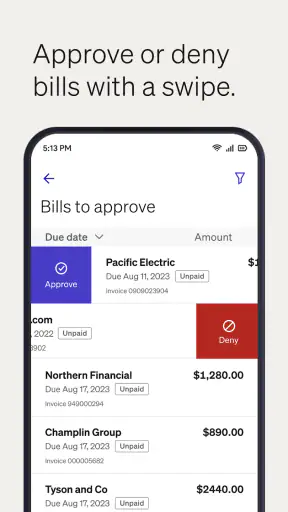
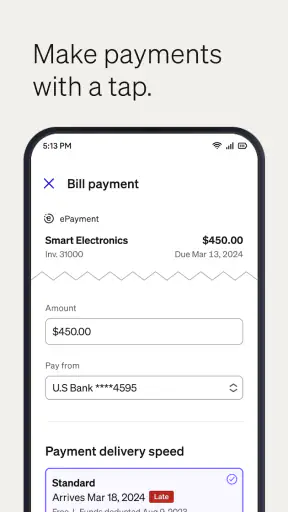
For outgoing bills, the most useful habit is to review each payment as a task with a purpose, not merely as a transaction. Before approving anything, I would check the vendor, amount, due timing and the business reason for the expense. A mobile screen encourages quick decisions, so this small pause is important. The app can make a process more convenient, but convenience should not turn into automatic approval of every request that appears.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
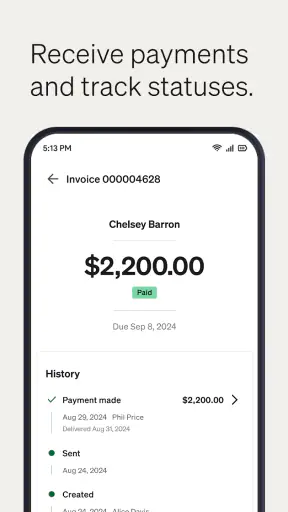
For incoming payments, the same principle works in reverse. Instead of waiting for money to appear in a bank account and then trying to match it to an invoice, a business can treat receivables as active work that needs follow-up. That is especially useful for a small operation where the person sending invoices is also the person checking whether customers have paid.
Why the combined AP and AR focus matters
Many ordinary banking apps are good at showing balances and moving money, but they are not designed around the day-to-day language of business bills and customer payments. A spreadsheet can track invoices, yet it depends on someone remembering to update it and interpret it correctly. Email can hold approvals and payment instructions, but important decisions become scattered across messages. BILL AP & AR makes more sense when the problem is not simply “how do I transfer money?” but “how do I keep business payment work organized?”
The trade-off is that a focused business payment app may feel unnecessary if your financial activity is very light. A freelancer with a handful of recurring clients and only a few monthly expenses might be perfectly comfortable with a bank app, accounting software or a simple spreadsheet. In that situation, adding another destination for payment work could create more maintenance than value.
Where it becomes more convincing is in the middle ground: a small company with enough invoices to lose track of them, but without a large finance department. The owner may need visibility into what is waiting to be paid, while another person prepares or monitors customer invoices. A dedicated AP and AR tool gives those responsibilities a clearer shape than a personal banking app usually can.
A realistic day with the app
Imagine a small design studio on a busy afternoon. The owner is visiting a client, a contractor’s bill needs attention, and a customer payment is expected soon. Instead of writing a note to deal with both items later, the owner can open the business payment app, review the outgoing bill and check the incoming payment work from the same general environment.
The benefit here is not dramatic automation; it is reduced friction. The owner can make a decision while the context is fresh, then return to the client meeting without carrying two unfinished payment reminders mentally. Later, the receivables side can be checked to see which customer payments still need attention. For a small team, that kind of continuity can be more valuable than a long list of advanced options that nobody has time to learn.
I would still keep a separate habit of recording why a payment was approved and checking the underlying invoice before acting. Mobile access is excellent for staying current, but it can also encourage shallow reviews. The best workflow uses the app for timely action while preserving careful financial judgment.
Useful habits that are easy to overlook
One non-obvious strength of a focused AP and AR app is that it can help separate payment visibility from payment urgency. Not every bill that is visible needs to be paid immediately, and not every unpaid customer invoice is already a crisis. I would use a quick review routine: first identify what requires action today, then distinguish items that simply need monitoring. This prevents the app from becoming a noisy list of financial reminders.
A second useful approach is to review outgoing and incoming work together at a set time. A business can feel profitable while waiting on customer payments, or feel cash-poor while several receivables are close to arriving. Looking at both sides encourages better timing decisions. It does not replace proper cash-flow planning, but it gives a more balanced view than checking bills alone.
Third, I would avoid making mobile approval the only control in a growing business. When more than one person is involved, the person who knows the expense should be able to explain it clearly before payment is finalized. BILL AP & AR is most helpful when it supports a defined internal routine, such as who reviews bills, who confirms them and who monitors incoming money. The app cannot invent that routine for you.
Where the experience may feel limited
The main weakness is not that the app focuses on business payments; that is its purpose. The limitation is that a focused payment tool may not satisfy someone looking for a complete business-finance workspace. If you expect detailed bookkeeping, broad budgeting, inventory management, payroll handling or a full accounting environment, you may need another product alongside it.
That can create a split workflow. Payment activity may live in BILL AP & AR while financial reporting and reconciliation happen elsewhere. For a very small business, maintaining two systems may feel like extra work. For a larger operation, the separation may be acceptable, but only if the team has a clear process for keeping records aligned.
There is also a human limitation: the app can make it easier to act, but it cannot decide whether an invoice is legitimate, whether a supplier’s details are correct or whether a customer’s payment should be chased today. Those decisions still require attention. I would not recommend treating a convenient approval screen as a substitute for checking source documents and business records.
Another point to consider is the learning curve created by business terminology. Someone familiar with accounts payable and accounts receivable will understand the structure quickly. A first-time business owner may need to learn the difference between managing bills and managing customer payments before the app feels natural. That is not a flaw unique to this product, but it affects how quickly a new user can benefit from it.
Who should use it, and who should choose something else?
I think BILL AP & AR is a strong candidate for small businesses that send invoices, receive customer payments and pay vendors regularly. It is particularly suitable when the owner or a small finance team needs to stay involved while working away from a computer. The app’s business focus is more relevant here than the broad feature set of a general money-management app.
It may also suit a growing service business that has outgrown informal payment tracking. If invoices are currently spread across email, folders and a basic spreadsheet, moving payment work into a dedicated app can make responsibilities easier to see. The improvement will be greatest when the team agrees on a consistent review rhythm rather than simply installing the app and hoping organization appears automatically.
I would be more cautious if your business has only occasional bills, does not invoice customers or already has a well-established accounting workflow that handles payments comfortably. In that case, a bank application or accounting platform may be simpler. I would also look elsewhere if your main need is deep financial reporting rather than payment management. The right alternative depends on whether your priority is banking convenience, bookkeeping depth or team-based payment control.
Before adopting it, I would ask four practical questions. Will the people responsible for bills actually use a mobile workflow? Do incoming customer payments need the same attention as outgoing expenses? Is there already another system that must remain the financial record of truth? And can the business define who reviews payment details before anything is sent? Clear answers will tell you more than the app’s download count.
Compatibility, cost and what to expect
The app is free, which lowers the barrier to trying it, but I would still evaluate the complete business process rather than judging it only by the installation cost. A free app can still require staff time, training and a supporting accounting routine. The real question is whether it saves enough time and confusion to justify becoming part of that routine.
It was released on December 16, 2015, and the current version is 3.7.171. The listed minimum operating system is 9, so users should check that their device meets the requirement before planning a rollout. I also recommend testing the app with the people who will actually handle bills and receivables, because a workflow that seems clear to an owner may feel different to an employee who processes payment requests all day.
Since the app is rated for Everyone, it is broadly approachable from an age-rating perspective. That should not be confused with unrestricted business access, however. A company should still decide which employees are allowed to view or act on payment information and should keep its internal approval rules clear.
My final assessment
After looking at how it fits into daily work, I see BILL AP & AR as a focused tool with a sensible purpose rather than a universal business-finance solution. Its best quality is the way it brings outgoing bills and incoming payments into the same business-oriented conversation. That can make a real difference for small teams that need to stay responsive without sitting at a desk.
The app is less persuasive for people who want accounting, reporting and every other financial task in one place. It also demands good habits: checking invoices carefully, defining approval responsibilities and keeping related financial records consistent. Those are not reasons to reject it, but they are reasons to use it deliberately.
My recommendation is straightforward: try it if your business regularly pays bills and follows up on customer payments, especially when mobile access would prevent work from piling up. Skip it if your needs are limited to occasional transfers or if your existing accounting system already handles the entire payment process well. For the right small-business workflow, this free Business app from Bill.com Inc. can turn payment administration from a scattered chore into a more manageable daily task.
In short, I would recommend it to a business owner who wants practical payment oversight, not to someone searching for a complete financial command center. Its value is clearest when the app becomes part of a disciplined routine: review what is due, verify the details, act on the right items and keep an eye on money coming in. Used that way, BILL AP & AR earns its place on a business phone.
Pros
- Streamlines invoice creation, tracking, and payment collection in one place.
- Helps reduce manual data entry and paper-based payment administration.
- Provides clearer visibility into outstanding receivables and payment status.
- Supports more consistent payment workflows for growing businesses.
- Can improve communication between businesses and their customers.
Cons
- May require setup time before existing billing processes can be migrated.
- Advanced features may depend on the selected subscription or service plan.
- Users may need accounting knowledge to configure invoices correctly.
- Payment processing availability can vary by country and supported providers.
- Businesses may need extra tools for full accounting or tax management.
FAQs for BILL AP & AR Business Payments
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. It can be used to send and receive invoices, schedule vendor payments, collect customer payments, organize transaction records, and improve visibility into cash flow. It is primarily intended for businesses rather than personal budgeting or everyday consumer payments.
Is BILL AP & AR Business Payments suitable for small businesses?
Yes, the platform can be useful for small and growing businesses that want to reduce manual payment work and keep financial processes more organized. It may help owners and accounting teams manage bills, invoices, approvals, and payment status from a centralized dashboard. However, available features, pricing, user limits, and accounting integrations can depend on the selected plan, business type, and region, so these details should be checked before signing up.
Can I connect BILL AP & AR Business Payments to accounting software?
BILL is designed to work alongside business accounting workflows and may support connections with popular accounting platforms, depending on the product and subscription plan. Syncing can help transfer bills, invoices, payment details, and vendor or customer information without entering everything manually. Before downloading or subscribing, review the current integration list and confirm that your accounting software and preferred version are supported.
Is BILL AP & AR Business Payments secure for business transactions?
The service is built for handling business payment and invoicing information, with account controls and security measures intended to protect financial data. Even so, no online platform eliminates every risk. Businesses should use strong, unique passwords, enable available authentication protections, limit employee permissions, and carefully verify payment details before approving transactions. It is also important to review BILL’s current privacy, security, and fraud-protection policies.
Does BILL AP & AR Business Payments charge fees for using the service?
Costs can vary according to the BILL product, subscription plan, payment method, transaction type, and business requirements. Some features may be included in a plan, while certain payment or expedited processing options may involve additional charges. Because pricing and fee schedules can change, users should consult the official BILL website or in-app account information before enrolling, particularly if they expect to process a high volume of payments.

BILL AP & AR Business Payments
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via feedback@hq.bill.com, visit http://www.bill.com, or review their http://www.bill.com/privacy/.










